Mortgage Broker Toronto
Personalized mortgage solutions for Toronto homebuyers, homeowners and investors.
Mortgage help in Toronto
Toronto mortgages come with their own realities: high purchase prices, competitive offers, condo and multi-unit financing rules, and renewal decisions that carry real dollars. SAITHBAR Mortgage is the practice of Swapnil Patel, a licensed Mortgage Agent Level 2 working with buyers, homeowners and investors across the city.
The approach is simple. Start with your actual numbers, understand what you may qualify for and what it would cost month to month, then review the options available through the lending network before you commit to anything.
Buying in Toronto
Toronto buyers pay both provincial and municipal land transfer tax, which changes how much cash you need on closing. Planning for that early keeps your down payment intact.
Condos and multi-unit
Lenders assess condos, duplexes and multi-unit properties differently than single-family homes. Property type can affect both qualification and your down payment requirement.
Renewals across the city
If your term is ending, your renewal letter is a starting offer. Reviewing it a few months early gives you time to compare without pressure.
Meetings that fit your schedule
Conversations happen by phone, video or in person at the Etobicoke office — whichever works for you.
Mortgage services for Toronto clients
Home Purchase Mortgages
Pre-approval, structure and payment planning before you make an offer.
Mortgage Renewal
Review your renewal letter against other options before you sign it.
Refinancing
Restructure your mortgage, consolidate debt or access equity.
Self-Employed Mortgages
Business-for-self income assessed by lenders in different ways.
Investment Properties
Down payment rules and rental income treatment for rentals.
Home Equity
Understand the equity you've built and how it may be accessed.
Run your Toronto numbers
Free to use, no personal information required to see results. Both calculators use Canadian mortgage math, including the stress test on affordability.
Mortgage Payment Calculator
Estimate your mortgage payment based on price, down payment, rate, and amortization. Uses Canadian semi-annual compounding.
These figures are estimates for educational purposes only and are not a mortgage approval or commitment to lend. Actual qualification, rates, terms, and approval depend on lender requirements and the details of a complete application.
How Much Home Can I Afford?
Estimated using standard Canadian debt-service guidelines (GDS 39% / TDS 44%) and a stress-tested qualifying rate.
These figures are estimates for educational purposes only and are not a mortgage approval or commitment to lend. Actual qualification, rates, terms, and approval depend on lender requirements and the details of a complete application.
What could improve your buying power?
- → A larger down payment increases your total budget.
- → Lowering monthly debt payments frees up qualifying room.
- → A different property price point may change insurance costs.
- → Changes in income directly affect what you can qualify for.
Want a professional review of your numbers?

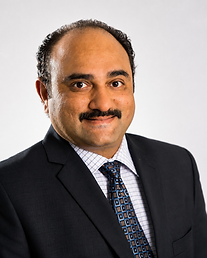
Meet Swapnil Patel
Mortgage Agent Level 2
Swapnil Patel is the licensed mortgage professional behind SAITHBAR Mortgage, working with Toronto clients on purchases, renewals, refinancing, self-employed income and investment properties. He works with Affinity Mortgage Solutions, part of the Dominion Lending Centres network, so applications are placed with lenders in that network.
Why work with SAITHBAR?
Personalized mortgage guidance
Your situation is reviewed by a licensed mortgage professional — not scored by a form and forgotten.
Options through a lending network
Applications can be placed with lenders available through Affinity Mortgage Solutions and the Dominion Lending Centres network.
Support through the process
From first conversation to closing, you have one point of contact who knows your file.
Secure client portal
Track your progress, message your agent and see what's outstanding, all in one private place.
Document management
Upload income and property documents securely instead of sending email attachments.
JARVIS AI assistant, plus a human
Ask JARVIS general mortgage questions any time — and reach Swapnil when the answer needs a professional.
Toronto Mortgage FAQ
How does mortgage pre-approval work in Toronto?
A pre-approval reviews your income, debts and down payment to indicate the mortgage amount you may qualify for, usually holding a rate for a set period. It is not a final approval — full approval depends on a complete application and the specific property. In a competitive Toronto market, it helps you shop inside a realistic budget and make offers with confidence.
When should I start looking at my mortgage renewal?
Roughly four to six months before your term ends. Starting early gives you time to compare your lender's renewal offer against other options and to move if a different structure suits your situation better. Signing the renewal letter without reviewing it is the most common missed opportunity.
Does refinancing make sense for a Toronto homeowner?
It depends on your goal and the numbers. Refinancing can be used to access equity, consolidate higher-interest debt, or restructure a mortgage that no longer fits. Costs such as penalties, legal and appraisal fees need to be weighed against the benefit, which is exactly what a review is for.
What do first-time buyers in Toronto need to know?
Three things: your minimum down payment (5% on the first $500,000 with a higher percentage above that), the closing costs on top of your down payment including Toronto's municipal land transfer tax, and the stress test, which qualifies you at a higher rate than the one you're offered. The first-time home buyer guide walks through each step.
Can I get a mortgage in Toronto if I'm self-employed?
Yes, in many cases. Lenders assess business-for-self income differently — some rely on your notices of assessment and averaged income, others accommodate alternative documentation. What you can qualify for depends on your full picture and the lender's requirements, so it's worth a conversation before you shop.
How much down payment do I need for a Toronto investment property?
A property you do not live in typically requires at least 20% down, and lenders differ in how much of the rental income they count toward qualification. Condo, duplex and multi-unit financing each follow their own rules.
More mortgage tools and pages
Let's look at your options
No cost, no obligation. Share your goal and Swapnil will walk you through what's possible.